Storm hit your roof? As your local Brandon roofer, we inspect the roof and attic, stop the water coming in and photograph every bit of damage. You’ll know exactly what needs fixing, what it will cost, and have clear records ready for your insurer.
Warning Signs
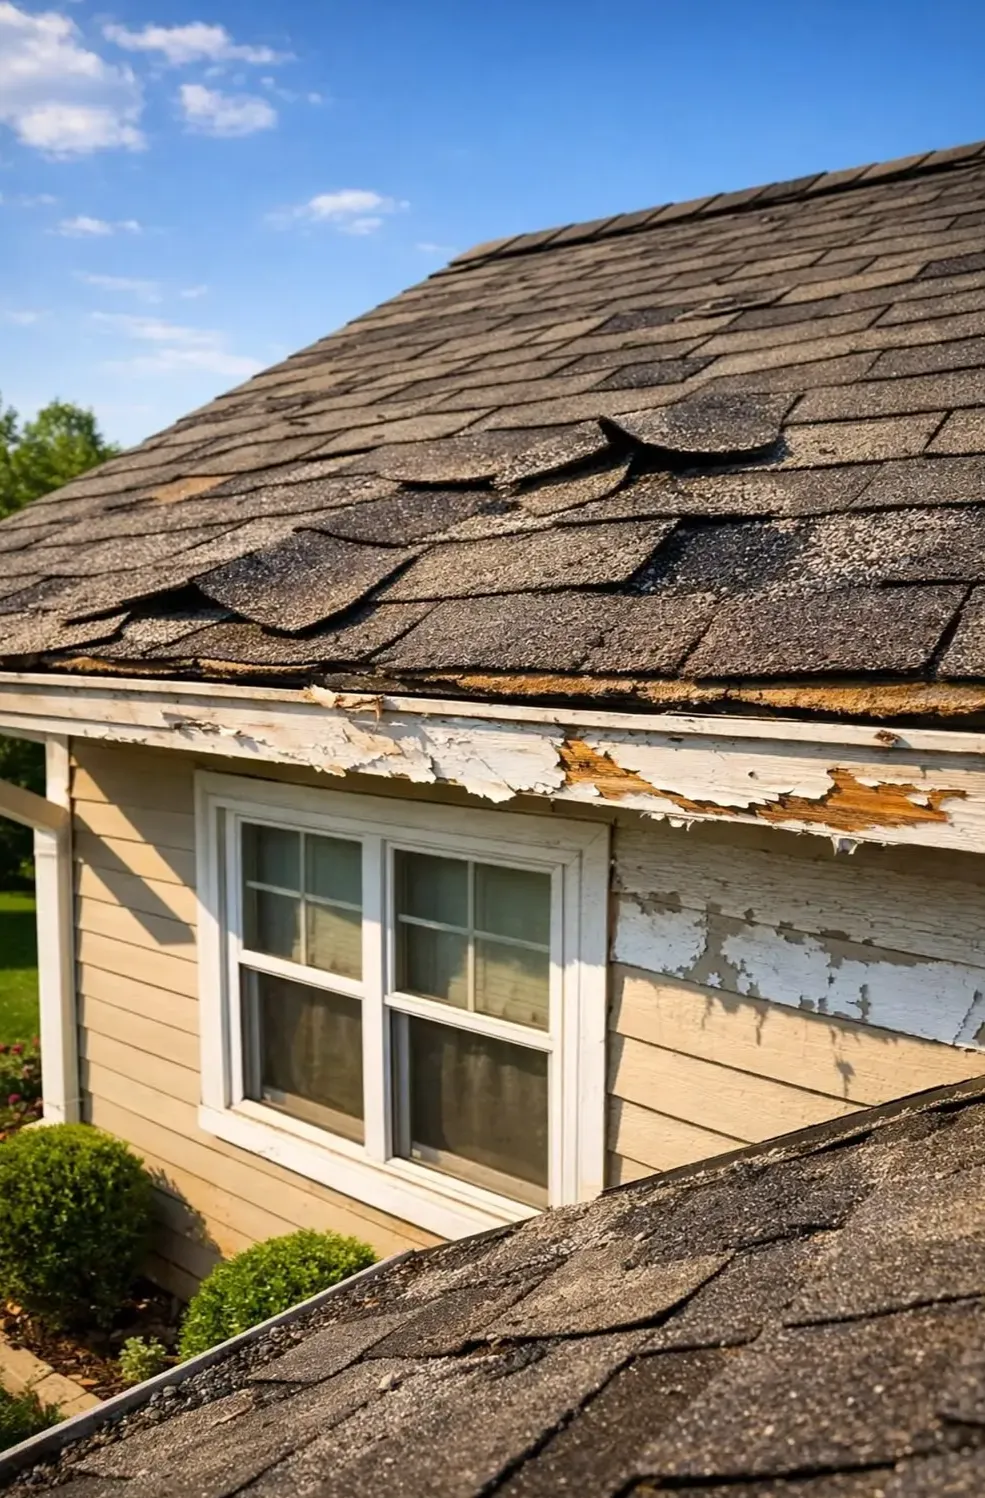
Wind damage is often invisible from the driveway. These are the signs we look for after every storm that rolls through Brandon.
01
Gaps on the roof, shingles in the yard or tabs that flap in the wind. Once the seal strip breaks, the next storm can peel them off.
02
A straight crease across a shingle means wind bent it back. It may look flat now, but it no longer sheds water the way it should.
03
A pile of sand-like granules at the downspouts after a storm means the shingle surface has been worn or beaten off.
04
Metal flashing and rubber pipe boots take the brunt of wind-driven rain. Small gaps here are where most storm leaks start.
05
A stain that appears days or weeks after a storm is a sign water is getting past the roof. It rarely sits right under the damage.
06
Even a small branch can puncture shingles or crack the deck. Check where limbs landed, even if they’ve rolled off.
91 mph
Peak gust at Tampa International Airport during Hurricane Milton
1 Year
Deadline to file a new or reopened property insurance claim in Florida
60 Days
Time your insurer generally has to pay or deny your claim
100 Days
Average days a year with lightning in the Tampa area
After the Storm
The first 48 hours matter. These steps protect your home and make your insurance claim easier.
01
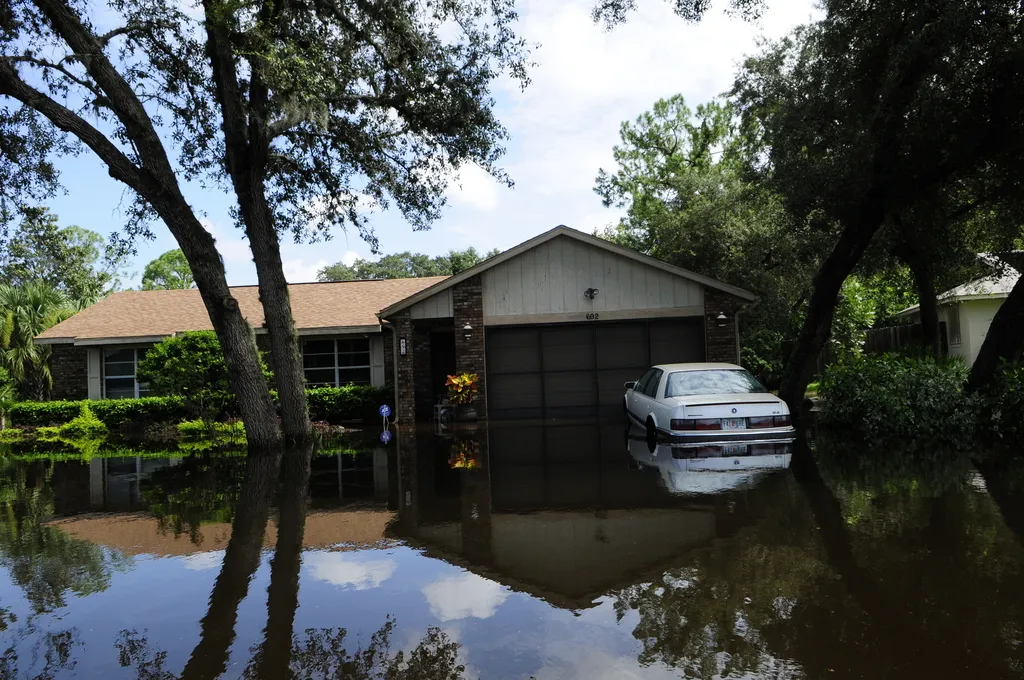
Stay off the roof and away from downed power lines. Wet shingles and broken decking are dangerous.
02
Take dated photos of the roof, yard debris and any ceiling stains before anything is moved or cleaned up.
03
Put buckets under drips and move belongings. A tarp on the roof limits further damage, and insurers expect you to take reasonable steps.
04
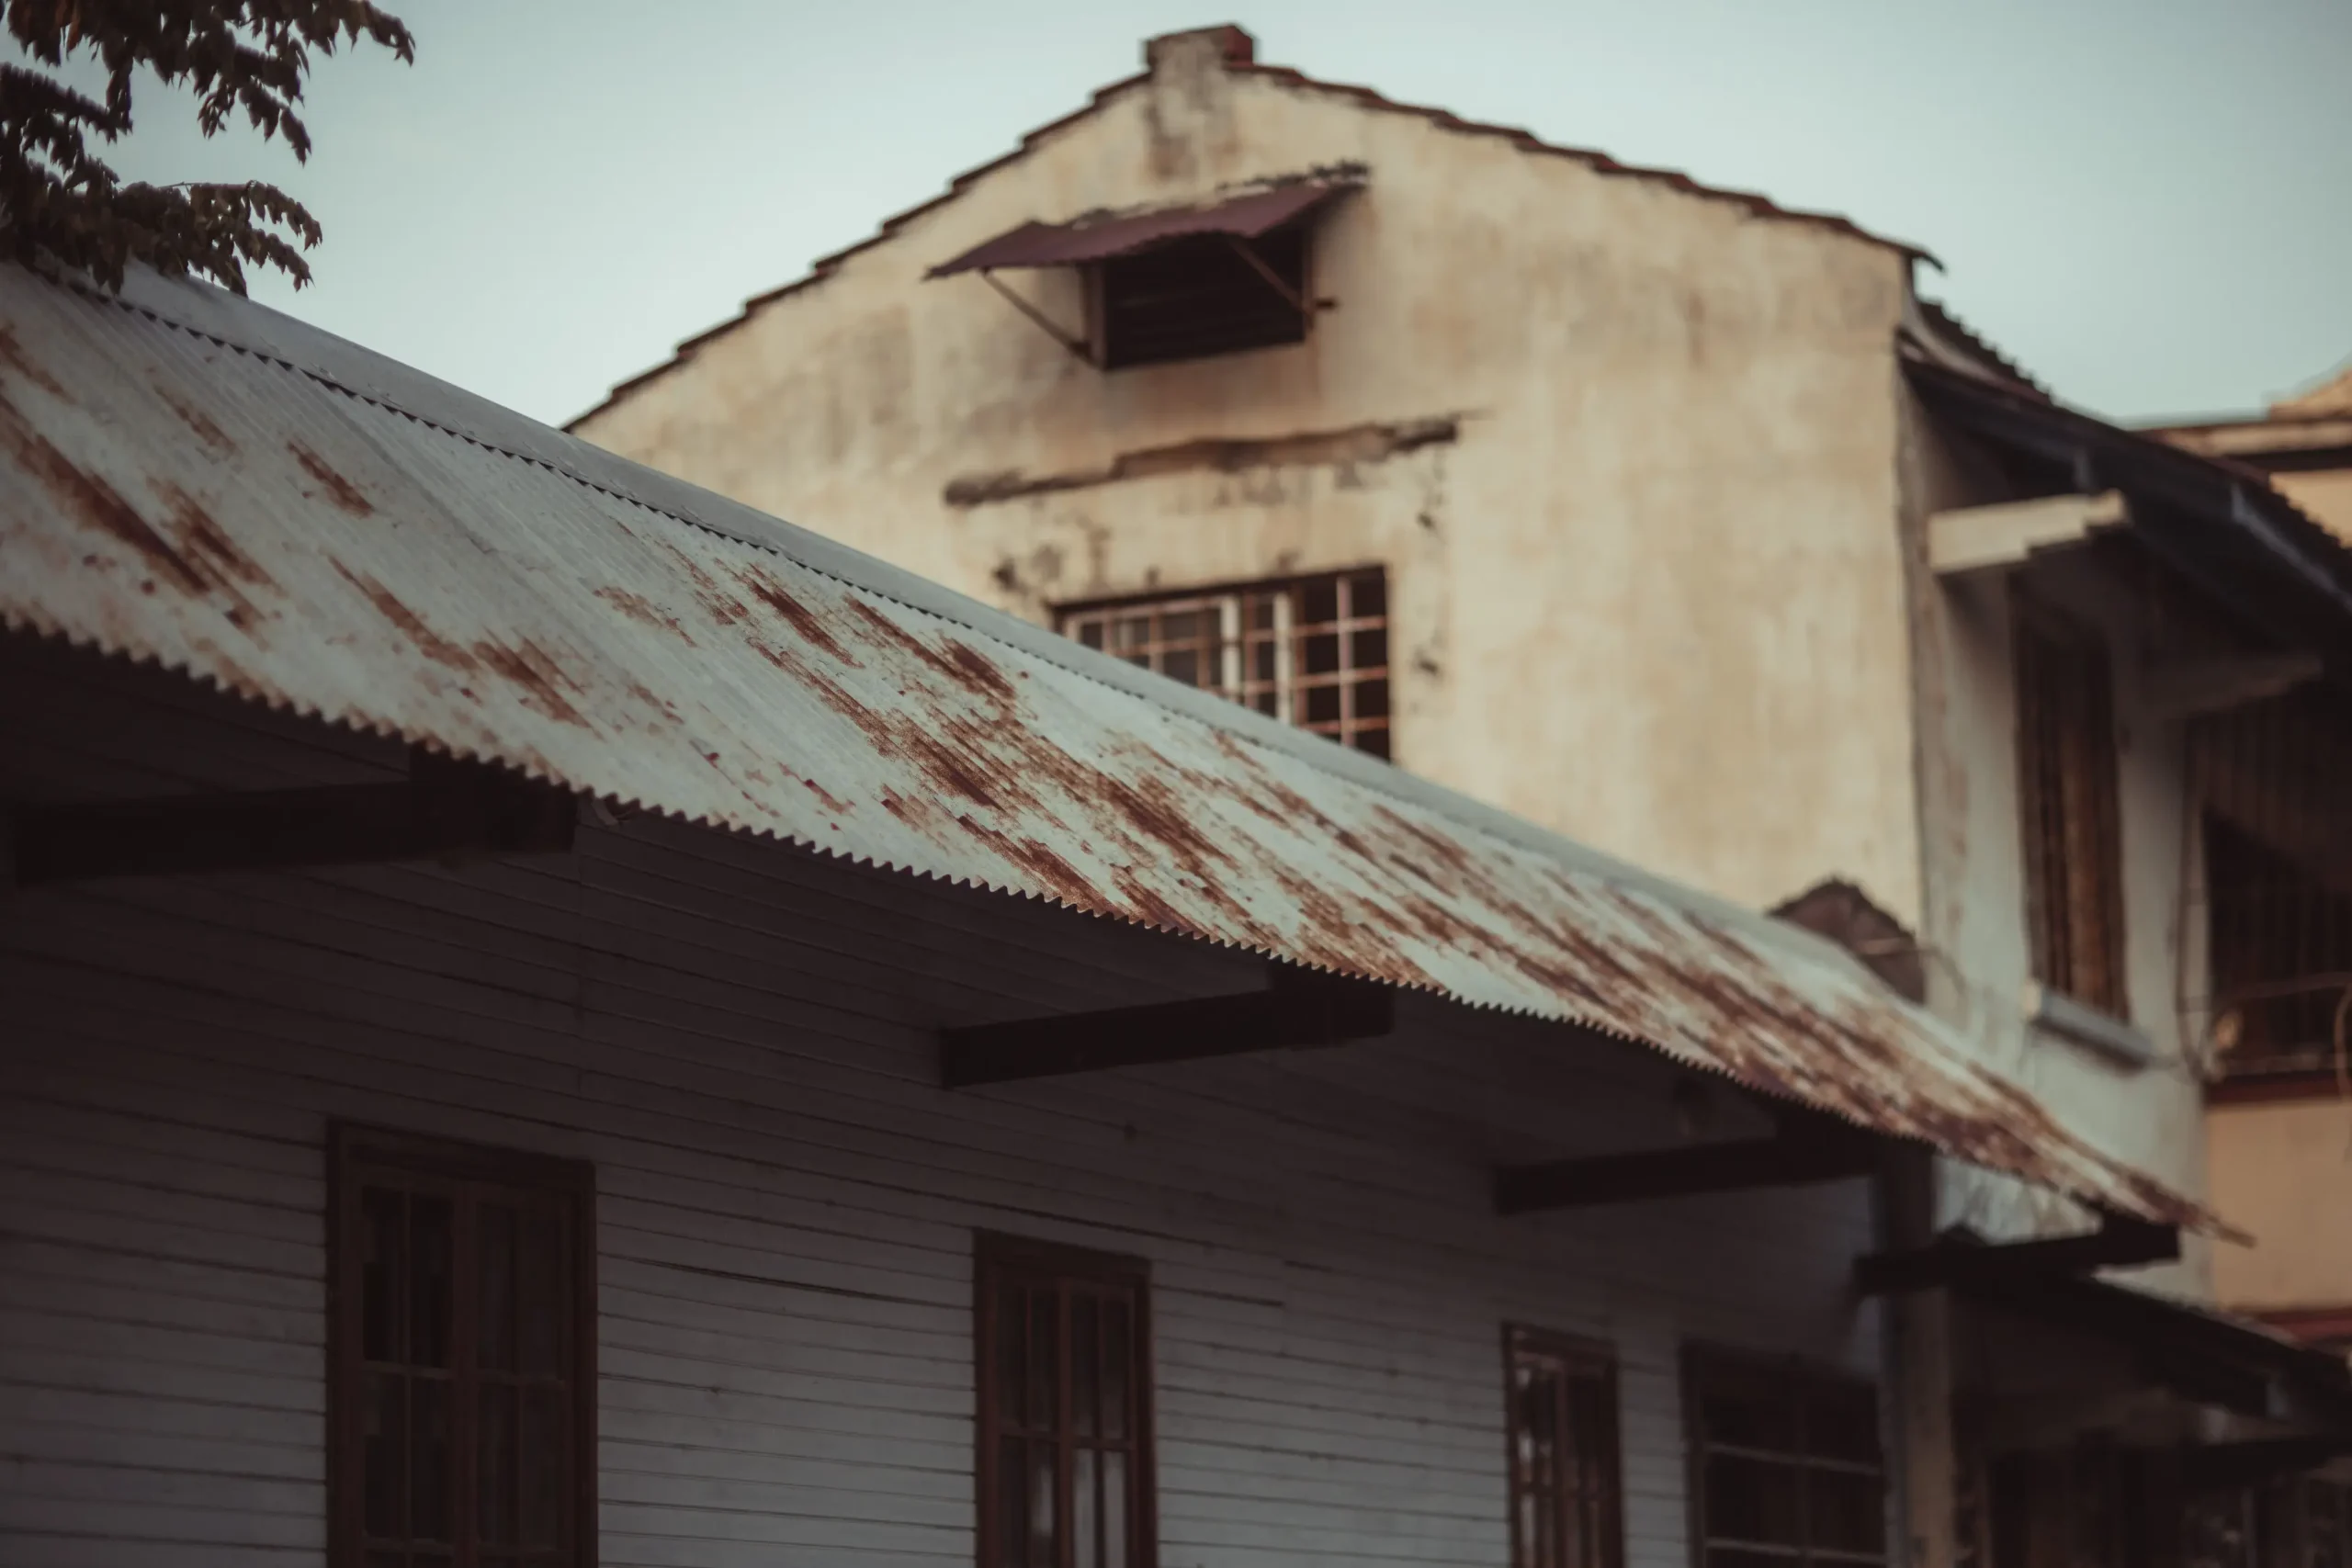
Call your insurer or file online. Keep the claim number and write down who you spoke to and when.
05
Tarps, temporary repairs, hotel stays and cleanup costs may be reimbursable under your policy.
06
Take your time. Storm chasers push for a quick signature. Get photos of the damage and a written estimate before you agree to anything.
Local Storm Risks
Brandon sits inland, but that doesn’t protect roofs from wind and rain. Here’s what we see here after big storms and ordinary summer weather.
Milton brought 91 mph gusts to Tampa’s airport and 11 to 14 inches of rain. Many Brandon roofs that looked fine afterward still have broken shingle seals.
Milton set a Florida record with 45 tornadoes in one day. Damage can hit one street and skip the next, so a neighbor’s roof is no guide to yours.
About 60% of our yearly rain falls June through September, in short, violent afternoon storms that drive water past flashing and pipe boots.
Tampa sees lightning about 100 days a year. Strikes and limbs crack shingles and decking in spots you can’t see from the ground.
Season runs June 1 to November 30. A small storm repair left for later often becomes a big one after the next named storm.
Need Help With Your Roof?
We’ll inspect your roof and give you a written quote. No obligation.
What We Do
From the first emergency tarp to the final repair, we handle the roof work so you can deal with everything else a storm leaves behind.
We check the roof and attic, trace leaks and photograph every damaged area. See how our roof inspection in Brandon works.
When water is coming in, we cover the damaged area with a secured tarp to protect your home until permanent repairs can be made.
Replacing blown-off shingles, resealing flashing, new pipe boots and deck repairs. Learn more about roof repair in Brandon.
When damage is widespread, a new roof may be the smarter fix. Read about roof replacement in Brandon.
Insurance
Florida tightened its claim rules for policies after 2022. You now have 1 year from the date of loss to report a new or reopened claim, and 18 months for a supplemental claim. Don’t wait for a leak to get worse before you call your insurer.
If a hurricane caused the damage, your hurricane deductible usually applies instead of your regular one. In Florida it’s typically $500 or 2%, 5% or 10% of your dwelling coverage. It applies from the time a hurricane warning is issued for any part of Florida until 72 hours after the last watch or warning ends, and only once per calendar year.
For policies issued on or after January 1, 2023, you can’t sign your insurance benefits over to a contractor. Be careful with anyone who asks you to.
New or reopened claim
1 year from date of loss
Supplemental claim
18 months from date of loss
Insurer acknowledges your claim
Within 7 days
Insurer inspects (if needed)
Within 30 days
Insurer pays or denies
Within 60 days
Sources: Florida SB 2-A (2022) and the Florida Department of Financial Services. Check your own policy for exact terms.
Your insurer decides what’s covered. Our job is the roof and the facts about it.
We don’t interpret your policy or negotiate your claim. For that, talk to your insurer, your agent or a licensed public adjuster.
You are responsible for paying your insurance deductible. Under Florida law it is insurance fraud, a felony, for a contractor to pay, waive or rebate any part of your deductible, and it is also fraud to file a claim with false or misleading information. Contractors can’t offer gifts, cash or rebates in exchange for an inspection or a claim (Florida Statutes 489.147).
Protect Yourself
After every big storm, out-of-town crews flood the Tampa Bay area. Most homeowners never see them again once the check clears. Watch for these signs.
Crews that show up uninvited after a storm, often with out-of-state plates, may be gone before the warranty matters.
It’s illegal in Florida. A contractor who offers it is telling you how they do business.
A contract or a claim document signed on the porch, before anyone has been on the roof, is a red flag.
Assigning your benefits to a contractor is banned for policies issued since January 2023.
Paying most of the job before materials arrive leaves you with nothing if the crew disappears.
Out-of-town crews often list only a cell number. If they can’t be reached after the job, neither can your warranty.
Repair or Replace
We’ll tell you which one your roof actually needs, and show you the photos that explain why.
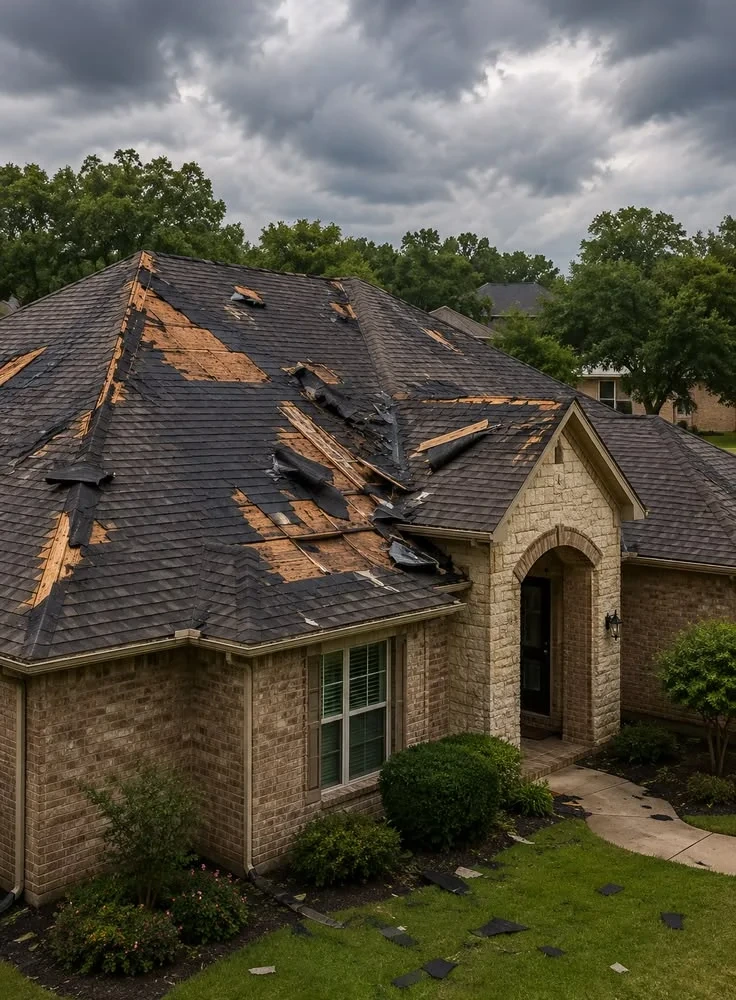
Most storm damage is limited to part of the roof: a section of blown-off shingles, bent flashing or a cracked pipe boot. Fixed quickly, the rest of the roof keeps its full life. Our roof repair work always starts here.
Florida’s 25% rule can require a full reroof when more than a quarter of a roof is repaired in a year, but only for roofs permitted before March 1, 2009 (Florida Statutes 553.844). Newer roofs can usually be repaired. If replacement makes more sense, we pull the Hillsborough County permit. Learn more about roof replacement.
How It Works
Clear steps and straight answers, from the first call to the final repair.
01
Tell us what happened and whether water is coming in.
02
If needed, we tarp the damaged area to protect your home.
03
We check the roof and attic and photograph all damage.
04
A clear repair or replacement quote you can share with your insurer.
05
Permanent repairs to Florida Building Code, with photos of the finished work.
FAQ
Answers to what Brandon homeowners ask us most after a storm.
Look for missing or creased shingles, granules piling up at the downspouts, bent flashing and new ceiling stains. Much wind damage can’t be seen from the ground, so an inspection of the roof and attic is the only way to be sure.
For most policies, 1 year from the date of loss for a new or reopened claim, and 18 months for a supplemental claim. Report damage as soon as you can, since waiting can also make the damage worse.
That depends on your policy and the cause. Sudden wind or storm damage is often covered, while normal wear and age usually isn’t. Your insurer decides. We give you the photos and written estimate to support your claim.
A separate deductible that applies to hurricane damage, usually $500 or 2%, 5% or 10% of your dwelling coverage. It applies once per calendar year. Check your declarations page to see which one you have.
No. Florida law makes it insurance fraud for a contractor to pay, waive or rebate any part of a deductible. Any roofer who offers to is putting you and your claim at risk.
Yes. If water is getting in, we can cover the damaged area with a secured tarp to protect your home until permanent repairs are done. Keep the receipt for your insurer.
A reroof always needs a Hillsborough County permit, and larger repairs may too. We’ll tell you if your job needs one and pull it for you.
All Brandon ZIP codes, including 33508, 33509, 33510 and 33511, plus Valrico, Seffner, Riverview, FishHawk, Lithia, Dover, Mango and Gibsonton.
Have these ready and your claim will move faster:
Need Help With Your Roof?
We’ll inspect your roof and give you a written quote. No obligation.